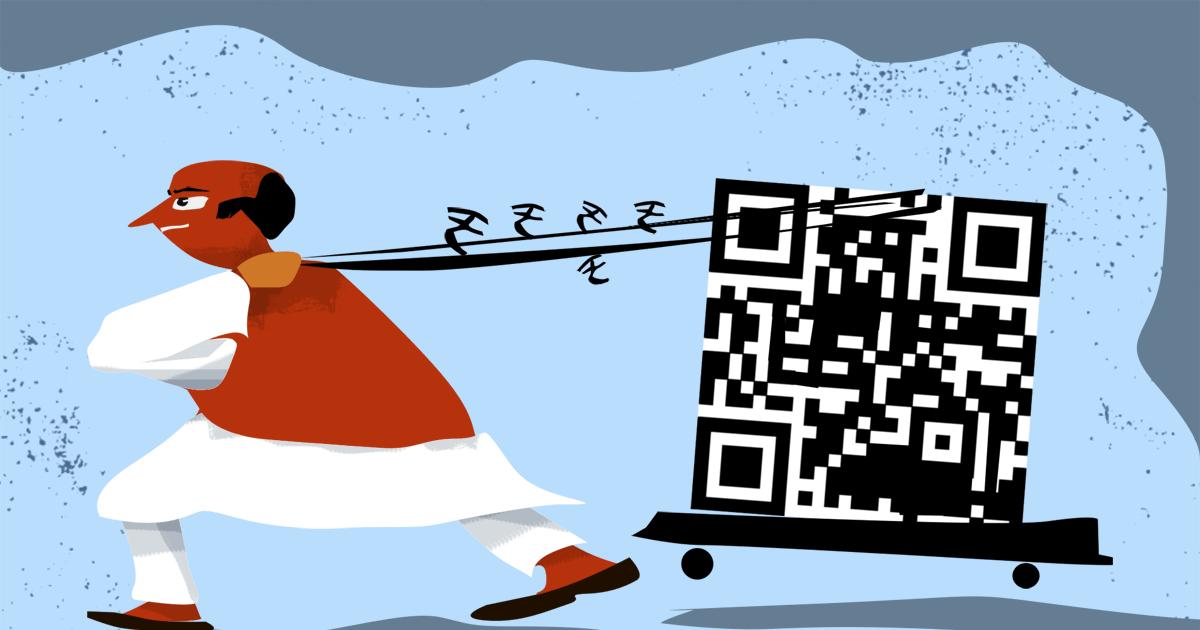





A new report by IIT-Bombay professors proposes a significant reduction in the Merchant Discount Rate (MDR) for UPI transactions, advocating for banks to fund the digital payment ecosystem from their substantial CASA deposit earnings to ensure its sustainability and public trust.
Key Points
- IIT-Bombay professors recommend cutting UPI MDR to 0.08 per cent from the current 0.40 per cent.
- The report suggests banks should fund the UPI ecosystem from their substantial net interest margins from CASA deposits, rather than relying on MDR.
- It proposes reducing credit card MDR and reconsidering free ATM withdrawal allowances to promote digital transactions.
- The paper argues against using the credit card’s ad valorem MDR model for UPI, suggesting a maximum cap of Rs 40 per transaction if adopted.
- To ensure public trust and sustainability, the report recommends restricting UPI ecosystem remuneration to merchants with an annual turnover of Rs 50 crore or more.
Merchant discount rate (MDR) on UPI transactions should be cut to 0.08 per cent from the present 0.40 per cent, a report by professors at IIT-Bombay has recommended.
In the report, Ashish Das, a professor in the institute’s Department of Mathematics, and Pragya Das, who was formerly with RBI, said that the third party application providers like PhonePe and Google Pay and payment service providers which are mostly banks should be compensated for their services.
It recommends a reduction in the MDR for the TPAPs to 0.06 per cent from the 0.08 per cent recommended by NPCI, and retaining the PSPs’ share at 0.02 per cent. In the present model, a bulk 70 per cent is split between the issuer and acquirer banks, the study said, arguing for removing this share entirely as banks are well compensated through the sacrifices on interest rates made by current and savings account depositors.
IIT-Bombay Recommends Lower UPI MDR
Banks booked over Rs 4.85 lakh crore in net interest margin (NIM) through CASA deposits in FY26, which is a “large and disproportionate” compensation for providing minimal free services.
“Banks earn substantial interest margins from the CASA depositors. They should use the same towards running and improving the UPI ecosystem and not rely on MDR revenue sharing from offline transactions,” it said.
To run and improve the UPI ecosystem, banks should carve out, say, about 3 per cent of the funds (Rs 15,000 crore) sacrificed by CASA depositors and not rely on MDR revenue sharing, it added.
Banks’ Role In UPI Ecosystem Funding
It also asked the RBI and government to provide directions on making UPI as part of necessary service to be provided to remain in the banking business (just like CBS was adopted and now a necessity for the banks).
The paper said a transaction cost of Rs 300 for a peer-to-merchant transaction of Rs 75,000 and above for an electronic transaction like UPI “raises a vital question of reasonableness of fixing such a high cap as service charge” and reminded that RBI regulations mandate a service charge which is not out of line with the average cost of providing a service.
It recommended a ‘digital payment fee’ for online merchant payment transactions made while purchasing an item or service from an e-commerce company.
Addressing Transaction Costs And Credit Card MDR
Pointing out that most merchants in the UPI MDR bracket levy charges for transactions over Rs 2,000 and also accept credit cards, it recommended reducing credit card MDR to address concerns that credit card users are burdening P2M UPI users.
It also asked the RBI to reconsider the “retention of generous fee free ATM withdrawal allowances” as this cannot be justified alongside availability of easy-to-use digital means for transacting, and also continuing the payments infrastructure development fund.
Continuing the PIDF will also help acquire newer merchants by payment aggregators, it said.
The paper argued that there appears to be “no rationale for the credit card’s MDR model to be used for UPI” and added that if the ‘ad valorem’ is adopted for UPI, the maximum cap should not exceed Rs 40 per transaction.
Ensuring UPI’s Public Trust And Sustainability
UPI, a public digital infrastructure, has generated significant convenience for users and productivity gains for the economy, with its long-term economic benefits outweighing the incremental income that could accrue from merchant transaction fees, the report titled ‘UPI at a Crossroads: Reintroducing the MDR’ said.
It cautioned that public trust in UPI could be undermined if the proposed MDR framework is implemented in its present form, stressing the need to ensure that the digital payments platform does not attract negative sentiment among users. The paper suggested that merchants with annual turnover of Rs 50 crore or more must provide UPI as a means of accepting payments.
Accordingly, the remuneration for the UPI ecosystem can be harnessed by restricting it only to merchants with annual turnover of over Rs 50 crore (about 4 crore per month), it said, adding that this would account for about 90 per cent of NPCI’s proposed MDR. There is a potential for NPCI to introduce a reasonable charge on merchants, within the legal mandate, across all online person-to-merchant (P2M) UPI transactions, it noted.
As per the National Payments Corporation of India (NPCI) circular issued last month, a 0.4 per cent Merchant Discount Rate (MDR) will apply to person-to-merchant (P2M) UPI payments above Rs 2,000.
Merchants, not consumers, will pay the charge, capped at Rs 300 for transactions of Rs 75,000 or more.
Payments between individuals, as well as the vast majority of everyday merchant payments, will remain free. Essential services, such as railways, telecom, fuel, and insurance, will attract a flat Rs 5 fee per transaction above Rs 2,000.
Capital markets transactions (mutual funds, stockbroking) get a lower 0.02 per cent rate, also capped at Rs 300. The NPCI, which operates the UPI platform, on September 15, issued a circular providing for MDR on certain UPI transactions, with the move aimed at creating a sustainable revenue framework for the digital payments ecosystem.
Disclaimer: News content is sourced from the stated source. Headlines, summaries, section headers, and images are automatically generated or selected using AI/algorithms and may not always be fully accurate. Readers are advised to refer to the full article for complete context.